
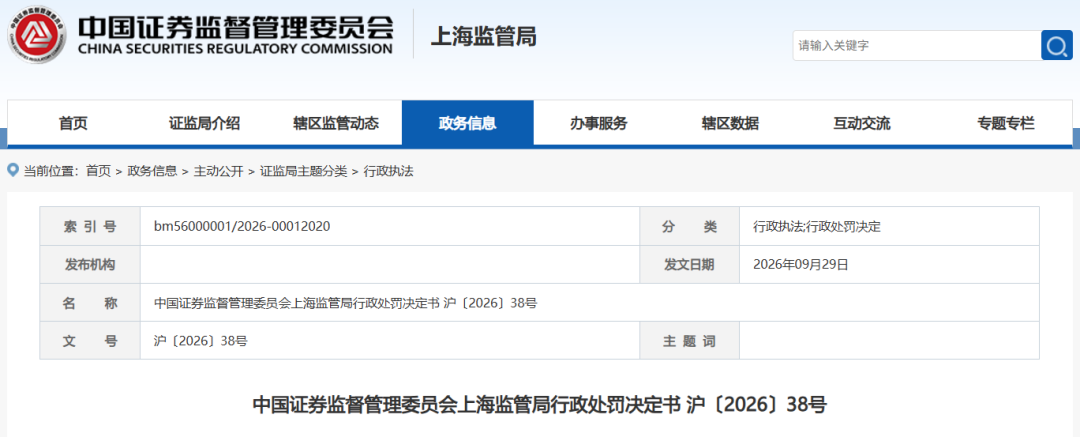
Recently, the Shanghai Bureau of the China Securities Regulatory Commission issued Administrative Penalty Decision No. Hu 2026 38 (original text available below), imposing penalties on Yun, a research analyst at an insurance asset management company, for trading based on undisclosed information (commonly known as "rat trading"). The penalty includes ordering the disposal of illegally held securities in accordance with the law and imposing a fine of 50 million yuan.
The penalty notice shows that Yun, a female born in 197X, is employed by an asset management company's research department as the portfolio researcher for the case. She was responsible for investment decisions and other duties related to the portfolio and had access to non-public information, including holdings and transaction details of the portfolio. The asset management company holds an insurance license.
Between 2022 and 1, Yun controlled two Everbright Securities accounts under the names "Huang Mouju" and "Zhu Mouxiang." Using non-public information obtained through their position, Yun engaged in securities transactions that mirrored those of the relevant portfolio, either independently or by directing others (explicitly or implicitly), resulting in losses. The funds in these accounts were primarily sourced from and directed to Yun and their spouse.
Ultimately, the Shanghai Securities Regulatory Bureau determined that Yun's conduct violated Article 54, Paragraph 1 of the Securities Law and constituted an illegal act as described in Article 191, Paragraph 2 of the Securities Law. Pursuant to Article 191, Paragraph 2 of the Securities Law and the preceding provision, insider trading using undisclosed information with no illegal gains or illegal gains under 500,000 yuan shall be fined between 500,000 and 5,000,000 yuan. As there were no illegal gains in this case, the penalty was set at the lower end of the range.
Insurance asset management companies are other financial institutions as referred to in this Article. Employees of such companies who use their positions to obtain non-public information for trading shall be subject to this Article.
The most intriguing aspect of this fine lies not only in the paradox of losing money while being penalized, but also in the individual's role. Although Yun was nominally a research analyst, they were deemed to be responsible for investment decisions regarding the portfolio in question. Typically, investment decision-making authority rests with fund managers, while analysts provide research support—a standard division of labor at most asset management firms. However, in some smaller and mid-sized asset management institutions, it is indeed common for research analysts to play an active role in investment decisions.
"This enforcement case confirms that the standard for identifying individuals with access to non-public information in capital markets is based on actual decision-making authority, not publicly listed job titles," said Bi Menglan, a researcher at GeShang Fund. In this case, Yun's public job title as a researcher was not used as the basis for determination. Regulators focused on the individual's actual work authority, finding that Yun participated in investment decisions for the portfolio involved, had access to non-public information such as portfolio holdings and trading plans, and was therefore classified as an insider.
Bi Mengran stated that China's asset management industry traditionally builds its information barrier systems based on job levels and departmental divisions. This conventional approach leaves clear regulatory blind spots. Although some research analysts and back-office support staff lack formal titles such as fund manager or investment manager, they are deeply involved in investment research decisions and have access to core trading data. Traditional information barriers only segment permissions by job labels, failing to cover personnel who substantively handle sensitive information, thereby creating compliance vulnerabilities.
Nan Kai University finance professor Tian Lihui also stated in an interview that current information barriers often rely on static role and departmental divisions, overlooking actual power overreach and cross-functional interactions during business workflows. Asset management firms must shift from defining confidentiality based on job positions to defining it based on authority, dynamically tracking information access trails and trade order flows, and precisely delineating the boundaries of persons with access to non-public information.
From a legal perspective, Dong Yaohui, rotating president of the Shenzhen Financial Stability and Development Research Institute, told Shanghai Securities News that this case reflects an enforcement approach to insider trading based on non-public information: any convergent trade executed using non-public information obtained through one's position constitutes a violation, regardless of profit or loss. Even if the trader incurred losses and had no illegal gains, the statutory minimum fine of 50 million yuan remains a mandatory penalty for the violation.
Typically, "mouse trading" occurs in licensed financial institutions that hold or have access to large investment portfolios, such as public and private funds. According to incomplete statistics, between 2021 and 2025, the China Securities Regulatory Commission (CSRC) initiated investigations into 42 mouse trading cases and transferred 17 of them to public security authorities. While public funds account for the highest number of cases, regulatory enforcement is gradually expanding to include insurance asset management and securities firms.
Why are "rat trading" penalties rare in the insurance asset management sector? Tian Lihui explains that scarcity of such penalties is not due to lower moral risk, but rather monitoring barriers stemming from long investment horizons, low transaction frequency, and complex account nesting.
However, regulatory barriers are being gradually dismantled by RegTech. Dong Yaohui believes that the nearly 4-year investigation and precise identification of illegal facts in this case demonstrate enhanced capabilities of regulators in detecting low-frequency convergence and constructing long-term behavioral profiles. RegTech can now detect anomalous trajectories within massive volumes of low-frequency transactions.
For asset management firms, Dong Yaohui recommends: close the gap in underlying account transparency reporting and identify hidden accounts held by employees and their related parties; break down internal data silos to establish a dynamic sensitive information blocking mechanism covering research, investment, and trading; and develop customized anomaly detection algorithms tailored to the low-frequency trading and long-term holding characteristics of asset management products, building a digital compliance defense aligned with your business logic.
"Defining sensitive information roles should not rely solely on job titles but on actual access to and influence over non-public information. Whether in research analysis, trade execution, risk control, or performance evaluation, any role that实质上 contacts or infers core holdings and trading intent must be classified as a sensitive position," said Dong Yaohui.
Original No. 2026 38:
Party: Yun, female, born in 197X, residing in Pudong New Area, Shanghai.
Pursuant to the relevant provisions of the "Securities Law of the People's Republic of China" (hereinafter referred to as the "Securities Law"), this Bureau initiated an investigation into Yun's use of undisclosed information for trading. The Bureau informed Yun of the facts, reasons, and legal basis for the proposed administrative penalty, as well as their statutory rights. No statements or defenses were submitted by the party, nor was a hearing requested. The investigation and processing of this case are now concluded.
The following violations by Yun were confirmed:
1. Yun was aware of the relevant non-public information
A certain asset management company (hereinafter referred to as "the Company") was granted an insurance license. Mr. Yun served in the Research Department of the Company as a researcher for the portfolio involved in this case, responsible for investment decisions and other related duties, and had access to non-public information regarding the portfolio's holdings and transaction details.
II. Yun controlled the securities accounts of "Huang [Name]" and "Zhu [Name]".
(I) Basic Information on Securities Accounts Associated with "Huang Mouju" and "Zhu Mouxiang"
The Everbright Securities account of Huang Mouju was opened at the Shanghai Century Avenue Securities Branch of Everbright Securities Co., Ltd. The Everbright Securities account of Zhu Mouxiang was opened at the Jinhua Binhong Road Branch of Everbright Securities Co., Ltd. The primary sources and destinations of funds in these securities accounts are Yun Mou and his spouse.
(II) Control of Securities Accounts Held by "Huang Mouju" and "Zhu Mouxiang" by Yun Mou
During the period from 2022 to 9 (hereinafter referred to as the Relevant Convergence Trading Period), Yun controlled securities trading accounts under the names "Huang Mouju" and "Zhu Mouxiang" at Everbright Securities to conduct relevant securities transactions.
III. Yun engaged in securities trading activities related to non-public information
During the period of the implicated convergent trading, Yun used non-public information about the involved portfolio obtained through his position, violated regulations, and either personally directed or instructed others to operate securities transactions in the "Huang Mouju" and "Zhu Mouxiang" Everbright Securities accounts. These actions resulted in convergent trading with the involved portfolio, leading to losses from such trades.
The above violations are supported by evidence provided by a certain asset management company, including relevant documentation, communication records, trading details of securities accounts, bank account fund statements, and interrogation transcripts of involved personnel, which are sufficient to establish the facts.
The Bureau finds that Yun's aforementioned conduct violated Article 54, Paragraph 1 of the Securities Law and constitutes an illegal act as described in Article 191, Paragraph 2 of the Securities Law.
Based on the facts, nature, circumstances, and social harm of the party's illegal acts, pursuant to Article 191, Paragraph 2 of the Securities Law, this Bureau decides:
Order Y to dispose of the illegally held securities in accordance with the law and impose a fine of 50 ten thousand yuan.
The parties listed above must remit the fine directly to the national treasury within 15 days from the date of receipt of this penalty decision. For specific payment instructions, please refer to the attached explanation in this decision. A copy of the payment voucher bearing the party's name must also be submitted for filing with the Office of the Administrative Penalty Committee of the China Securities Regulatory Commission (CSRC). If a party disagrees with this penalty decision, they may apply for administrative reconsideration to the CSRC within 60 days of receiving this decision (applications may be sent via express mail to the Legal Affairs Department of the CSRC), or file an administrative lawsuit directly with the competent People's Court within 6 months of receiving this decision. The execution of this decision shall not be suspended during the reconsideration or litigation proceedings.
Shanghai Bureau of China Securities Regulatory Commission
2026-9-29
We recommend "Fun Financial Thinking." In this world, everything relates to finance. The goal of learning finance isn't just to train accountants; it's first to cultivate a rational "economic man." Like watching magic versus performing it—two different worlds. Many people struggle to understand how a coin passes through glass. This book offers deep insights into financial phenomena, revealing that the magician is actually holding another coin in their hand.


