
Get a year of insurance for free without spending a cent? This seemingly too-good-to-be-true offer is actually a carefully crafted scam. Recently, a misappropriation case in Wuxi revealed the truth: an insurance sales team of 5 members used "free insurance" as bait to fabricate over 231 policies in less than a year, illegally pocketing more than 35 yuan in commissions. All 5 individuals were sentenced.
The events date back to the time when Liu served as the manager of District 1 at a Wuxi branch of a life insurance company. He recruited four fellow villagers, including Chen and Shi, forming his own team. Soon, they discovered that to rapidly capture market share, the company offered substantial incentives for new teams: if the team's total premiums reached over 20 ten thousand yuan, the combined commissions paid to all team members could exceed 20 ten thousand yuan.
After discovering this "shortcut," 5 people began aggressively hiring sales agents to expand their team structure. They instructed new agents to recruit friends and family willing to cooperate with insurance policies, offering a bait: one year of free insurance at no cost, with premiums prepaid by Liu and 5 others.
Most of these acquaintances lack the intention to purchase insurance independently and have little understanding of insurance companies; they simply agreed to cooperate because it was "free." Once the policyholder is identified, 5 transfers the prepaid premiums into the policyholder's bank account, and the insurance system automatically deducts the amount to generate the policy. When the insurance company distributes commissions to the agent's salary card, 5 recollects the reward funds in bulk. After deducting the initial premium costs, the remaining profit is split equally among them.
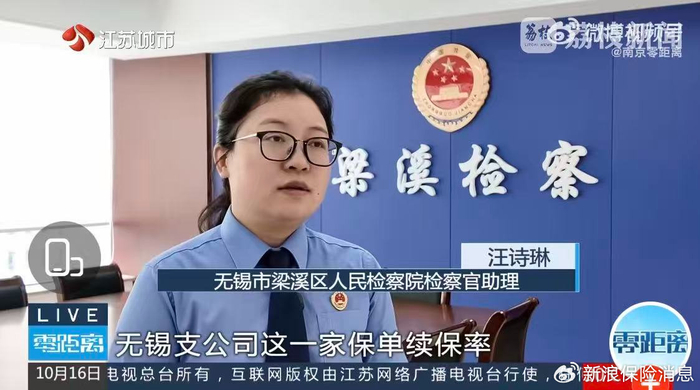
After one year, most of these fake policies were either terminated or surrendered. According to industry insiders, renewal rates for critical illness insurance are typically high, with an industry average ranging from 80% to 90%. However, during a review at the head office, the insurer discovered that the renewal rate for this team in Wuxi was abnormally low and concentrated entirely among the 5 individuals led by Liu and others. Further investigation revealed a large number of fraudulent policies.
After arriving at the station, Liu and 5 other individuals truthfully confessed to all criminal facts. Upon verification by the investigating authority, within less than a year, 5 individuals forged 231 insurance policies, fabricated premium sales totaling over 220 ten thousand yuan, and defrauded insurance companies of various rewards such as business commissions totaling over 35 ten thousand yuan.
Recently, the court sentenced Liu and 5 others to one year and two months in prison, with a one-year-three-month probation period, and imposed fines for each.
"Free lunches" often hide traps. This case exposes loopholes in insurers' performance incentives and policy verification mechanisms, while warning practitioners: do not reach out, or you will be caught.


