
Source: Xianlian She
The quality of service isn't measured by how a company treats Dong Yong, but by how it treats every ordinary driver who calls in calmly and without fame.
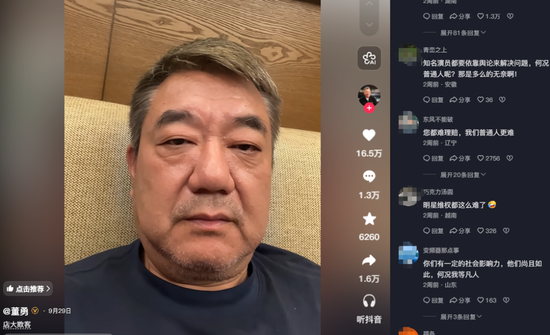
After a lifetime of playing police officers, Dong Yong probably never expected that at the age of 58, he'd need to post a video to handle his car insurance renewal.
It's actually quite simple. In 8 this year, Dong Yong renewed his mandatory traffic insurance. When it came time to process the commercial insurance online, the platform refused to let him proceed, displaying a message that he "already had insurance processed" and required manual handling. He called his agent, who simply replied, "Wait for the company to contact you."
He waited a full month. He made countless calls and sent numerous messages, but either received no response or found the replies unsatisfactory.
One month later, Dong Yong posted a video with the caption "Big Store Bullying Customers." Just an hour after it went live, Pacific Insurance quickly called to apologize.
He ultimately chose to cancel his policy and switch companies, willing to go through the hassle just to "stand up for himself."
The top comment on this video resonated with many: "Even famous actors have to rely on public opinion to resolve issues—what a helpless situation for ordinary people!" Another heartbreaking comment added: "If those with social influence are treated this way, how much more so for us commoners?"
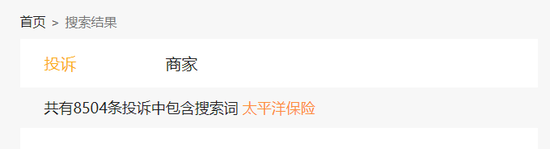
This isn't an exaggeration. On the Hei Mao Complaints platform [Download Hei Mao Complaints App], complaints about Pacific Insurance auto insurance services are rampant, totaling over 8 500.
Flip through casually, and you'll find encounters nearly identical to Dong Yong's.
On one side, there are claims of policy renewal being passed off and cashback payments delayed; on the other, Pacific Insurance is reporting impressive performance.
In the first half of 2026, the company achieved total operating revenue of 2121.36 billion yuan, a year-over-year increase of 5.8%. Net profit attributable to parent company shareholders was 307.75 billion yuan, up 10.4% year-over-year. The combined ratio for property and casualty underwriting was 95.1%, an improvement of 1.3 percentage points compared to the same period last year, significantly enhancing underwriting profitability.
This "Combined Ratio" is easy to understand: for every 100 in earned premiums, 95.1 goes toward claims and expenses, leaving 4.9 as underwriting profit. The lower the ratio, the more profitable the underwriting.
This isn't inherently wrong, but it becomes concerning when viewed alongside Dong Yong's experience: the buck-passing in renewal processes, the absence of human support, and complaint channels that are effectively useless. How much of these "cost savings" has been extracted from ordinary customers' service experiences?
That said, objectively speaking, the system bug Dong Yong encountered might be beyond the direct resolution capabilities of frontline insurance staff. As explained by an industry insider in the comments section, national auto insurance underwriting relies on a unified Zhongbaoxin platform; when system issues arise, insurers must report them to the platform for handling. This explanation is reasonable.
But the real question is: over the entire month, did anyone from the insurance company proactively tell Dong Yong, "We're looking into this"? Did anyone provide a clear timeline? Did anyone offer an informative response when he repeatedly called?
Nothing at all. It wasn't until he posted a video that it got resolved within an hour.
The most uncomfortable part of this whole situation isn't the bug itself, but the attitude behind it—clearly treating users differently based on who they are.
To put it plainly, the root of the issue isn't an individual agent's competence or a single system failure. The real problem is that the insurer's complaint handling mechanism accelerates under "public pressure" but slows down by default for "ordinary customers."
This isn't a capability issue; it's a priority issue. Corporate resources always skew toward "more likely to cause trouble"—a celebrity posting a video is trouble; a regular customer making a complaint call is not.
Conclusion
Dong Yong ultimately decided to surrender his policy and switch companies. For him, the loss was just one month of hassle and a small difference in premiums.
For an average car owner without traffic or followers, failing to renew commercial insurance for a month means the vehicle is effectively uninsured. Any accident during this period could result in losses of tens of thousands or even hundreds of thousands of dollars. The time, energy, and emotional toll of a month's worth of delays and blame-shifting are incalculable.
Service quality isn't measured by how it treats someone like Dong Yong, but by how it treats every ordinary car owner who calls calmly and has no fame.


