
Source: Guan Chao Finance
Guan Chao Analysis: With the listing of SPIC Life Insurance's Shanghai branch, changes to Shanghai Life Insurance's business registration, Mi Chunlei stepping down, Ma Xudong assuming the role of legal representative, and a proposed change in the acting general manager of SPIC Life Insurance... Shanghai Life Insurance is approaching its final phase. The three-year risk mitigation effort has reached the eve of "transition." Moving forward, how will SPIC Life Insurance break the vicious cycle of difficulty in generating revenue for distressed insurers? Can it forge a path unique to Shanghai? The market watches with anticipation.
According to an exclusive report by GuanChao Finance, Tai Fuchun, the proposed general manager of SPDB Life Insurance, may not receive regulatory approval for his qualification due to special circumstances. This marks another key leadership change for the company, which is still under construction, just before its official launch.
On 10 9, Pudong Life Insurance Shanghai Branch was officially registered. Nine days earlier, on 9 30, Shanghai Life Insurance completed its business registration change: Mi Chunlei stepped down as legal representative, with auditor Ma Xudong taking over and assuming a director role. On the same floor, two new signs—risk resolution has entered its final critical phase before the "switch."
Over the past three years, this resolution process has unfolded: In 2023 year 8 month, CPIC Life's Business Guidance Team deployed to Shanghai Life Insurance; in 2025 year 12 month, Xingqi Hengtai, the承接 platform with a capital of 106.41 billion yuan, was established; and in 2026 year 2 month, Pu Yin Life completed its business registration. To date, no insurance license or key executive qualifications have been publicly disclosed.
Recently, regulatory consolidation has accelerated rapidly, with Shanghai Life Insurance entering the final countdown. Three key questions arise: What happened in the past month? What is the background of this company? And how have asset disposal practices for risk entities evolved—from Anbang and Tomorrow Group to Shanghai Life?
The tide ebbs and flows in Pujiang; three years of towers rise on a single decree.
The old commander hands over the seal and departs from the former camp; the new team takes office and stands in an empty stronghold.
Two plaques from the same school still warm; a thousand sails across years wait for orders yet to come.
Changing a name doesn't change the essence; watch for the undercurrents where the waters seem calm.
01
Two signs on the same floor
Recently, Guan Chao Finance learned exclusively that the regulatory approval for Tai Fuchun's appointment as General Manager of Pudubank Life Insurance may not be granted due to special circumstances. The replacement candidate has already emerged and will also come from CPIC.
Notably, the transition of the general manager at the headquarters level and the corresponding implementation actions at the branch level are advancing within nearly the same timeframe, with recent activity intensifying. Pu-Yin Life Insurance is moving forward, while Shanghai Life Insurance is stepping back.
Branch-level挂牌
On 10 9, Pudong Life Insurance Shanghai Branch was officially registered, with Liu Bingkui as the person in charge. The registered address is Floor 8, No. 201 Century Avenue, China (Shanghai) Pilot Free Trade Zone. This marked nearly eight months since the parent company completed its business registration on 2 10.
Liu Bingkui joined China Pacific Life Insurance in 1996. He previously served as Section Chief, Deputy Director, and Director of the Office at the Zhejiang Branch; Deputy General Manager of Wenzhou Central Sub-branch; and General Manager of Jinhua Central Sub-branch. In 5 of 2009, he became General Manager of Hangzhou Central Sub-branch. In 4 of 2012, he was appointed Deputy General Manager of the Zhejiang Branch, Party Secretary and General Manager of the Gansu Branch. In 7 of 2023, he became Party Secretary and General Manager of CPIC Life's Changsha Operations Center.
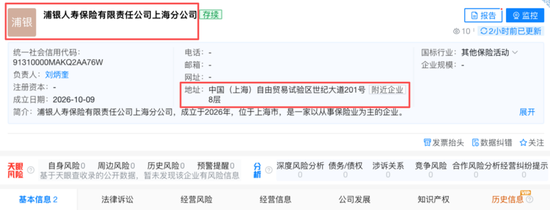
Liu Bingkui is a veteran of CPIC Life Insurance: joined the company in 1996, starting as Section Chief at the Zhejiang Branch office, then serving as Deputy General Manager of Wenzhong Zhongzhi and General Manager of Jinhua Zhongzhi. In 2009, he took over as General Manager of Hangzhou Zhongzhi in 5. During his tenure, total standard premiums at Hangzhou Zhongzhi rose to fourth place company-wide, and the individual insurance operation model in Xiaoshan was named the "Xiaoshan Model" by headquarters.
Served as Deputy General Manager of the Zhejiang Branch from 2012 to 4, and was subsequently transferred to Gansu Branch as Party Secretary and General Manager. Since 2023, has served as Party Secretary and General Manager of CPIC Life Changsha Operation Center.
An experienced branch leader is deployed to the frontline of a new entity to manage existing business. The objective is clear: the Shanghai Branch serves as the implementation hub for the new entity's transition and as its primary interface for assuming legacy operations.
Almost simultaneously with the establishment of Shanghai Life Insurance's Shanghai Branch, attention was drawn to its address. The branch was founded on 2018/9/20, under the leadership of Li Nai. Its registered business premises are located at Unit 01-04, Floor 8, and District 01, Floor 13, No. 201 Century Avenue, China (Shanghai) Pilot Free Trade Zone.
Two legal entities share physical space at the 8 level. This is not just spatial overlap, but a clear snapshot of the transition between the old and new entities.
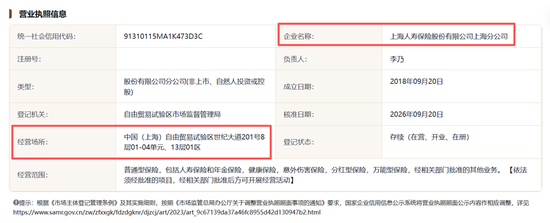
It is important to note that the registered addresses of the two entities are not "exactly the same," but rather both located on floor 8. Shanghai Life Insurance's Shanghai Branch's registration scope also includes floors 13 and area 01.
More significantly, the headquarters of Pudong Life Insurance is registered at 201 Century Avenue, Floor 27 (public information), while Shanghai Life's headquarters occupies Floors 12 and 13 in the same building. One building, three floors—housing the past and future of this resolution.
Notably, the business registration information for both SPIC Life Insurance's headquarters and its Shanghai branch was accessible around 10/10, after which both entries became unavailable. Under the current regulatory environment, a life insurer can only officially commence operations upon issuance of its license; all prior corporate actions are merely preparatory, not completed.
To understand where this "preparation" stands, we need to go back nine days — on 9/30, the old entity completed a prepared procedural closure.
A prepared procedural wrap-up
On 2026/9/30, Shanghai Life Insurance completed five business registration changes in one go: filing of the articles amendment, liaison officer registration, supervisor registration, director registration, and change of legal representative. The legal representative was changed from Mi Chunlei to Ma Xudong.
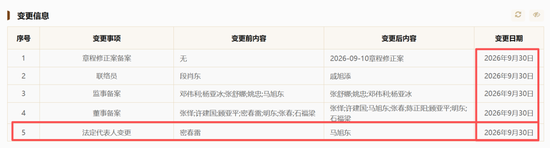
Mi Chunlei: Male, born in 1978, from Chongming, Shanghai. He graduated from Tongji University with a degree in Civil Engineering and Architecture and earned an EMBA from the CK Graduate School of Business. In 2003, he founded Lanhai Holdings (Group) Co., Ltd. and served as Chairman; he later also concurrently served as Chairman of Lanhai Medical Industry Investment Co., Ltd. Since 3 2015, he has held the position of Chairman of Shanghai Life Insurance Company. Prior to this resignation, his tenure exceeded 11 years.
Ma Xudong: Male, born in 1977. Previously served at Gansu Road & Bridge Construction Group; from 2006 to 2015, worked at the Gansu Bureau of Insurance Supervision as a section chief. Since 2021-7-2, has served as Audit Officer at Shanghai Life Insurance. Currently holds the positions of Director and Legal Representative at Shanghai Life Insurance.
Two earlier points clarify the nature of this change.
On 2026 year, 9 month, and 14 day, the Shanghai Financial Regulatory Bureau issued the "Reply on Amending the Articles of Association of Shanghai Life Insurance Co., Ltd." (Hu Jin Fu [Year 2026] Document No. 667), approving the amendment of relevant clauses in the company's articles of association.
On 9 28, the bureau issued the "Reply on the Qualification of Ma Xudong as Director of Shanghai Life Insurance Co., Ltd." (Hu Jin Fu [202026] No. 700), approving Ma Xudong's qualification as director and requiring the company to ensure his appointment within 2 months from the date of the administrative licensing decision, with a report submitted within 10 days after the appointment.
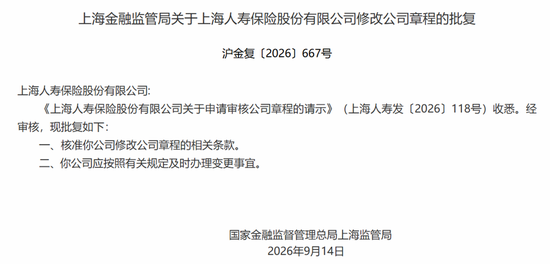

Qualification approval precedes registration. The business change on 9/30 is a comprehensive, procedural closure—not an emergency arrangement.
A key detail to note: According to business registration records, Ma Xudong has assumed the role of legal representative and director. The appointment for chairman of Shanghai Life Insurance remains pending. Per regulatory requirements, the qualifications for an insurance company chairman must be approved separately.
Therefore, characterizing this change as a "direct handover by the Chairman" is inaccurate. In practice, such a handover isn't feasible. A more precise description is that, during the winding-up phase of the original entity, a trusted legal representative who can fulfill their duties and sign documents is required.
Ma Xudong worked at the Gansu Bureau of Insurance for nearly a decade. He joined Shanghai Life as its Audit Responsibility Officer in 2021 year, 7 month, and five years later became the company's legal representative. From a procedural standpoint, his appointment may be one of the final operational actions by the original entity at the business registration level.
As the legacy entity wraps up its transition, the new management's top priority has emerged. With three years of risk mitigation approaching the "switching" threshold, "SPDB Life Insurance" is stepping forward. Whether it can truly stand firm and move forward depends not on business registration records, but on regulatory approvals, the capital contribution window before 11/29, and the coordination between the incoming and outgoing leadership teams.
However, the business registration change on 9/30 was merely a procedural closure. The real issue is: why did the original entity need to reach this "closure" stage? To answer that, we must look back at Shanghai Life Insurance under Mi Chunlei's leadership.
Michun Lei's Departure
Under Mi Chunlei's leadership, Shanghai Life Insurance was once the fastest-rising dark horse in the industry. In its inaugural year of 2015, gross premiums reached 144.89 billion yuan; by 2016, they surged further to 228.52 billion yuan, comprising 108.59 billion yuan in original insurance premiums and 119.93 billion yuan in new deposits for policyholder investment accounts, with universal life accounting for 52.4% of the total. The company turned a profit just one year after its launch.
At the time, it not only secured "Shanghai" as its company name but also assembled a core management team with impressive backgrounds. As time rolled on, all that remained was a fleeting brilliance and enduring heavy burdens: In 2016 year 5-8 month, the former China Banking and Insurance Regulatory Commission launched a special inspection of universal life insurance policies across 9 companies and issued regulatory letters; Shanghai Life Insurance was among them.
At the end of 12 in 2021, Mi Chunlei was taken away by local economic crime investigation authorities. He briefly resumed his duties afterward, but there has been no official announcement since then. Since then, Shanghai Life Insurance has not released its annual report; starting from 2022, it has also stopped disclosing solvency reports, with its website's latest annual report remaining at the 2020 edition.
The numbers weighing on this former chairman continue to mount...

China's Court Execution Information Disclosure Network shows that, as of this report, Mi Chunlei has received 58 consumption restriction orders. According to public records, the total amount involved in his cases is approximately 49.89 billion yuan, and the total amount enforced against Lanhai Holdings, which he effectively controls, is approximately 86.3 billion yuan.


Langhai Holdings' equity stake in Shanghai Life Insurance, exceeding 50 billion yuan, has been frozen by multiple courts in several rounds. The figures above reveal a straightforward reality: the original entity can no longer operate normally.
An Overlooked Schedule
The key clue to why "Switch" is slow lies in the platform's own business registration information.
As the establishment vehicle for SPDB Life Insurance, Shanghai Xingqi Hengtai Enterprise Management Partnership (Limited Partnership) was established on 2025-12-12 with a capital contribution of 106.41 billion RMB. The executive partner is Shanghai Ruijingheng Enterprise Management, and its principal place of business is located at Room 205, West Zone, 2nd Floor, No. 707 Zhangyang Road. Its approval date is 2026-9-22.
Managing Partner: Shanghai Ruijingheng Enterprise Management, established on 2025/11/19, with registered capital of 100 million RMB. It is 100% owned by Shanghai Guosheng Group Education and Technology Investment. Registered address: Room 202, Building 1, Lane 11, No. 1352, Yuyuan Road, Changning District; approval date: 2026/9/11.


Xingqi Hengtai's partner structure shows: SPDB Capital committed 62.07 billion RMB with 58.33098% equity; Shanghai International Group committed 26.74 billion RMB with 25.12922% equity; CPIC Life Insurance committed 9.56 billion RMB with 8.98412% equity; Shanghai Lujiazui (Group) committed 8.03 billion RMB with 7.54628% equity; Shanghai Ruijingheng Enterprise Management committed 100 million RMB with 0.0094% equity. The final deadline for all five parties to complete their capital commitments is 2026/11/29.

View the timeline compressed: The platform's architecture was built between 2025 Month 11 and 12, but it wasn't fully operational until mid-to-late 2026 Month 9.
This 9-to-10 month "idle period" is key to understanding the overall transition timeline. While actions like business registration and management team finalization can proceed as planned, critical milestones such as platform licensing approval, executive qualification vetting, and actual capital deployment each have their own schedules and uncertainties.
From a timeline perspective, every step in the path of Pudian Life was not slow: deployment of the working group, platform setup, management team finalization, headquarters registration, and branch establishment—all tightly linked. However, the cumulative "waiting time" between each step added up to form the "three-year" figure.
02
Shanghai and SPDB: The Journey and the Return
Three years have passed in the blink of an eye. Shanghai Life, once a young "dark horse," has now surpassed 10 years in history and can be simply divided into three phases: the rapid growth and loss-of-control period, the guidance team stabilization phase, and the new entity assumption period.
Phase 1: Surge and Loss of Control (2015-2020)
Shanghai Life Insurance was established in the Shanghai Free Trade Zone in 2015 2, becoming the first national life insurance company registered within the zone. With an initial registered capital of 20 billion yuan, it was jointly founded by 10 companies, including Lanhai Holdings (Group), COSCO Shipping Investment, and Shanghai Electric Holding Group. Following a capital increase that brought in new shareholders, the total number of shareholders increased to 13. Lanhai Holdings is the largest shareholder, holding 20% of the equity.
The company rapidly scaled its universal life products with high costs and short cycles: 2015 annual premium volume reached 144.89 billion yuan, of which new policyholder investment payments totaled 100.88 billion yuan, accounting for 69.63%; in 2016, annual premium volume hit 228.52 billion yuan, with the universal life share dropping to 52.4%.
In 2016, the company increased its registered capital from 20 billion to 60 billion yuan with approval from the former China Insurance Regulatory Commission and added three new shareholders: Yangning Industrial, HeCui Industrial, and Shanghai Xinglian Trading.
Two years later, the former CBRC issued a "Decision on Revocation of Administrative License," determining that relevant shareholders had concealed related-party relationships, held shares beyond the permitted proportion, and submitted false materials in their capital increase application. The approval for this capital increase was revoked, and they were ordered to return the non-compliant equity.
The root of the problem lies in equity ownership. When it's unclear who the shareholders are, the board of directors, internal controls, and related-party transaction oversight all fail.
Phase 2: Stabilization and Risk Mitigation (2021-2025 years)
In Q3 of 2021, Shanghai Life Insurance's comprehensive risk rating dropped to Class C, with a quarterly loss of 2.78 billion yuan in Q4. By the end of 2021, reports emerged that the actual controller had been detained; since then, the company has ceased publishing its annual and solvency reports.
In 2023, relevant Shanghai authorities launched a risk resolution initiative. In 8 of that year, CPIC Life joined as the business guidance team, led by Tai Fuchun, then Assistant General Manager of CPIC Life. The team focused on clearing channel businesses, controlling related-party transactions, and restructuring operations.
This "guidance" lasted over two years, during which the company's solvency remained unimproved and operations were effectively sustained on a maintenance basis.
Phase 3: Platform and New Setup (End of 2025 to Present)
On 2025/12/12, led by SPDB and joined by Shanghai International Group, CPIC Life, and Lujiazui Group, a total of 106.41 billion yuan was contributed to establish Xingqi Hengtai, the primary sponsor of Pudong Bank Life Insurance. On 2026/2/10, Pudong Bank Life Insurance completed its business registration with registered capital of 150 billion yuan and Zhang Jian as legal representative.
At the beginning of 3, Guanqiao Finance exclusively learned that the core management team was finalized: Zhang Jian as Chairman, Xia Yunping as Party Secretary, and Tai Fuchun as General Manager. In 9, the platform's qualification approvals were completed successively. On 30 9, the old entity concluded its business registration procedures. On 9 10, the Shanghai branch was officially launched.
Three stages, three keywords: Out of Control, Maintain, Prepare to Switch.


Reading down the "Person" column reveals a clear dividing line: the core figures of the old regime ended on 2026/9/30, while those of the new regime began in 2026/2.
03
From Anbang to SPDB: The Evolution of Asset Disposal Solutions
As yet another insurer approaching a transition point, if we place Pudai Life within the framework of risk resolution in the insurance sector, it is neither the first nor the last. However, the "solutions" for handling such cases have already evolved through several generations so far.
Solution 4: From Regulatory Intervention to Multi-Party Relay
First Generation: "Regulatory Takeover + Fund Capital Injection." Led by regulators, a takeover team was formed to fully assume control of operations, with the Insurance Security Fund contributing 608.04 billion yuan. This approach is highly administrative and delivers rapid results, but it also consumes the most public funds.
Second Generation: "Regulatory-led + Multi-party Collaboration." As the number of troubled institutions grows and fund contribution capacity shrinks, full funding is no longer feasible.
The approach to handling distressed insurers has evolved since the intervention in the "Tomorrow Group" companies: In 2020 and 7, the former CBIRC took over Tianan Life Insurance, Huaxia Life Insurance, Tianan Property & Casualty Insurance, and Yi'an Property & Casualty Insurance. Subsequently, new entities were established with joint funding from the insurance guarantee fund and leading insurers or central state-owned enterprises to assume their operations—
Rui Ren Life Insurance, with a registered capital of 565 billion CNY (Jiuzhou Qihang Fund 60%, Insurance Security Fund 40%), was approved in 2023 to fully acquire Huaxia Life's business and assets/liabilities in 11.
Zhonghui Life Insurance assumes Tianan Life Insurance;
Yi'an Property Insurance has been taken over by BYD and renamed BYD Property Insurance.
This generation is characterized by the fact that almost all of the new company's senior executives come from large state-owned insurance companies involved in the restructuring.
Third Generation: "Local State-Owned Enterprises Take the Lead." Hengda Life Insurance, Tianan Property & Casualty, and Junkang Life Insurance all belong to this category. This period is characterized by the typical principle of "each party takes responsibility for its own assets."
Evergrande Life is assumed by Harbor Life. Its shareholders include the Insurance Security Fund, governments of Shenzhen and Guangdong provinces, state-owned enterprises in Chongqing, and Taiping Life Insurance.
Tian'an Property Insurance is assumed by Shenneng Property Insurance, with registered capital of 100 billion yuan. The controlling shareholder, Shenneng Group, holds 50% equity. This follows a risk isolation path of "new establishment assumption + bankruptcy."
The path to Jun Kang Life Insurance has matured: Fuzze Life was approved for establishment in 2025 month 1 and approved for operation in 6 (insurance license approval date: 6 month 10; issuance date: 11 month 7). Registered capital is 170 billion yuan. On 12 month 4, it was approved to acquire Jun Kang Life's insurance business and corresponding assets and liabilities. Jinan Golden Investment Holding Group holds 49.71% and Jinan Zhengjin Tongda holds 3.53%, with local state-owned capital in Jinan collectively holding 53.24%, achieving absolute control.
The fourth generation is Shanghai Life Insurance — Putin Life Insurance. This single case differs from others like Ruizhong, Haikang, and Shenneng.
Five "New" Aspects: How This Order Differs from Previous Ones
A closer look reveals a clear evolution in disposal models: from direct fund guarantees to local state-owned capital leading with market-driven operators; from "preserving the brand" to "transforming the core." Pushing Life Insurance has advanced five steps further along this trajectory.
First, the lead role shifts to a "bank-affiliated" entity. Previously, the responsible party was either an industry guarantee fund combined with top-tier insurers or a local state-owned capital platform. In this case, SPDB Life is led by Shanghai Pudong Development Bank (SPDB) as its controlling shareholder—via Star Qi Heng Tai, which indirectly holds equity stakes in SPDB Life. SPDB has subscribed to 62.07 billion yuan, representing 58.33% of the platform's capital.
Prior to this, Shanghai Pudong Development Bank had already established presence in banking, wealth management, trust, and fund sectors. With the long-awaited acquisition of an insurance license, it completes its final strategic piece and further expands the lineup of bank-affiliated insurers in China.
Whether the capital strength and channel capabilities of bank-affiliated entities are truly compatible with the long-term liability management of life insurance remains to be validated in this model.
Second, the "Special Purpose Vehicle" is now positioned earlier. Xingqi Hengtai is a limited partnership with a capital contribution of 106.41 billion yuan, funded by four entities: SPDB Bank, Shanghai International Group, CPIC Life Insurance, and Lujiazui Group. Shanghai Ruijingheng serves as the general partner.
The market widely views this structure as a "firewall" to shield major shareholders' performance from the initial operational pressures of Shanghai Life's asset-liability portfolio.
Separating "assumption" from "equity holding" at the legal entity level is the most notable aspect of this transaction's structure.
Third, the boundaries of "new establishment and assumption" are being defined more rigorously. Based on public information and industry analysis, once SPDB Life Insurance receives approval to commence operations, it will assume all businesses, assets, and liabilities of Shanghai Life Insurance in their entirety. Concurrently, branch offices will be renamed and personnel transferred, ultimately leading to Shanghai Life Insurance's exit, deregistration, or rebranding.
This is a completely different path from "equity restructuring with continuation of the original entity": risks remain in the old shell, while operations are moved into the new one.
Fourth, a "cut-and-replace" approach to personnel. Unlike Shennan Property & Casualty Insurance's commitment to unconditionally absorb all employees and dispatched workers from Tian'an Property & Casualty Insurance, Pudai Life Insurance's leadership team is primarily drawn from the Shanghai Pudong Development Bank and China Pacific Life Insurance systems.
According to GuanChao Finance, most members of Shanghai Life Insurance's former management team are not included in the new entity's staffing; their arrangements, along with those of broader long-serving employees, will be clarified as the transition progresses. The determination and handling of historical operational responsibilities will proceed cautiously and systematically in accordance with applicable laws, regulations, and supervisory requirements.
"New company, new leadership, new system"—a more comprehensive approach than "retaining talent and stabilizing operations," but one that demands greater stability during the transition.
Fifth, the funding schedule is now set in stone. The final deadline for all five partners of Xingqi Hengtai to commit their capital is 2026/11/29. This means that even if all administrative procedures are completed within the year, there is still a clear window awaiting the actual inflow of funds.
Business registration can be initiated first, but qualification approval, appointment approvals, and capital contributions each follow their own independent timelines. This approach is characteristic of Shanghai.
04
Conclusion: The journey begins after the last signature.
When taking over a troubled insurer, what truly matters isn't "who takes the lead" or "how it's done."
When SPIC Life Insurance entered the market with a registered capital of 150 billion yuan and a lineup backed by local state-owned assets and banks, the greater challenge lay in learning from past cautionary tales—from Anbang to Tomorrow Group, from Dajia, Ruizhong, Zhonghui, Haigang, to Fuzé...
A series of cases reveal that the true test for new entities begins after launch: How to eliminate the outdated practices of legacy teams, can they truly achieve self-sustaining growth, and what mechanisms best rejuvenate these new organizations? This is not just a challenge for Pudong United Life Insurance but a microcosm of the industry's efforts to mitigate risks and overcome difficulties.
Only when the tide recedes do we see who is on shore and who is in the water. The ultimate outcome of risk resolution is never about changing a brand name, but about replacing it with a sustainable operating mechanism. In this sense, only after the old entity signs its final deal does the new one begin its journey.


