
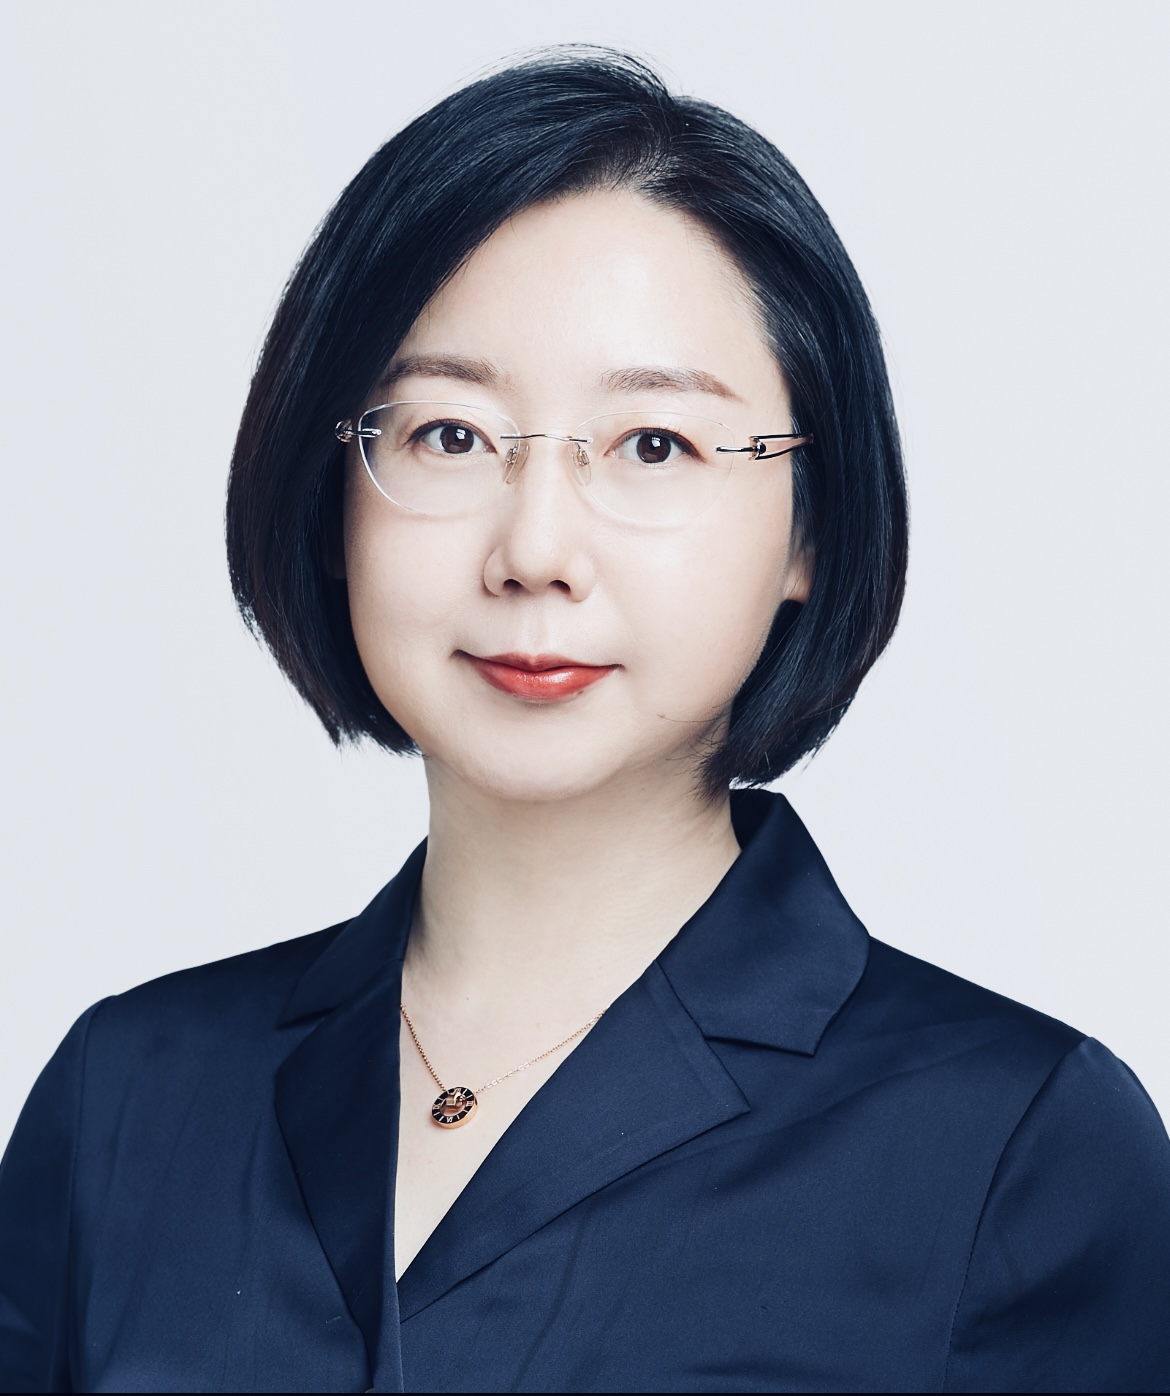
Cailian Press, 9 month 30 (Reporter Xia Shuyuan)
"Longevity risk is not merely a deviation in actuarial assumptions; it is a critical factor eroding insurers' capital efficiency and solvency. Its transmission chain is both concealed and lagging. If ignored, it will directly constrain business expansion and risk resilience," said Guan Jiaoyang, Chief Actuary and Chief Risk Officer of Minsheng Life Insurance, in an exclusive interview with Cailian Press during the Third Longevity Risk and Capital Market Solutions Conference hosted by Hunan University.
Guan Jiaoyang further emphasized that, driven by demographic shifts and the expansion of the pension market, longevity risk has become a critical challenge for the entire industry. She recommended that insurers establish dynamic monitoring and stress-testing mechanisms for longevity risk, proactively build capital buffers, and optimize product structures to effectively address the long-term challenges posed by population aging.
CLS: What is the relationship between longevity risk and insurers' financial stability?
Guan Jiaoyang: Longevity risk has not fully materialized, masked by interest rate hedging. However, its cross-cycle nature, macro-driven dynamics, and inherent volatility are posing severe challenges to insurers' long-term capital management.
As China's population structure evolves and the pension market expands, longevity risk is becoming a critical challenge for the insurance industry.
Guan Jiaoyang stated that "longevity risk" refers to the risk where an insured person's actual lifespan significantly exceeds the life expectancy assumptions in actuarial models, substantially increasing the insurer's future obligations for survival benefits.
Notably, this major risk has not yet fully manifested.
Guan Jiaoyang acknowledged that longevity risk has not yet fully manifested in industry calculations due to interest rate hedging and masking effects. However, a deeper analysis reveals that as one of the most fundamental and challenging risks in life insurance and annuity businesses, it directly impacts insurers' long-term financial stability.
First, it is a long-term issue involving cross-cycle exposure. Similar to interest rate risk, longevity risk spans the entire life of the insured—often decades. Currently, there are no perfect short-term financial instruments available for full hedging, placing extreme demands on insurers' long-term fund management capabilities.
Second is relevance, driven in depth by the macro factor of societal aging. Guan Jiaoyang emphasized that when the population structure was predominantly young and critical illness insurance was the primary product, the industry rarely discussed this issue; however, as China's population aged 65 and above now accounts for over 15% of the total, the exposure to longevity risk products will expand with increasing aging.
Third is uncertainty, stemming from forecasting errors. Factors such as advances in medical technology and rising living standards are difficult to quantify precisely, leading to discrepancies between actual mortality rates and actuarial assumptions. Medical experts predict that over the next 15 years, significant breakthroughs in medical technology may make reaching age 120 no longer a distant dream. This unpredictable forecasting error significantly increases pricing challenges for insurers.
Guan Jiaoyang believes that longevity risk is a major, cross-cycle, macro-driven challenge filled with uncertainties. In the era of increased longevity, preparing in advance and building adequate financial reserves is not only essential for insurers' stable operations but also a necessary path for every individual to navigate aging with confidence.
Cailianshe: How does longevity risk affect solvency?
Guan Jiaoyang: Increased longevity risk exposure forces insurers to supplement life insurance liabilities, expanding the liability base passively and eroding net assets. This intensifies capital consumption and puts pressure on solvency.
Guan Jiaoyang pointed out that there is a clear disconnect between capital measurement of longevity risk and current business practices.
In the Three-Pillar regulatory framework established under C-ROSS Phase II, Pillar I "Quantitative Capital Requirements" serves as the core defense line. Its quantified risks primarily cover three categories: insurance risk, market risk, and credit risk. Among these, longevity risk falls under the "Loss Incidence Rate" sub-category within insurance risk.
It is important to recognize that the impact chain of longevity risk on solvency is highly隐蔽.
The initial trigger is faster-than-expected improvement in mortality rates, which disrupts the original actuarial balance. Increased longevity risk exposure forces insurers to increase life insurance liability reserves, leading to a passive expansion of liabilities that directly erodes net assets and may cause actual capital to decline. Under the C-ROSS II framework, the minimum capital requirement for longevity risk rises in tandem with the exposure. Given the formula "Actual Capital / Minimum Capital," a shrinking numerator combined with an expanding denominator could put downward pressure on core solvency ratios.
"Under current rules, we primarily consider the impact of increased capital requirements due to expanded exposure, without yet accounting for the additional effects arising from dynamic adjustments in adverse scenarios following capital increases," noted Guan Jiaoyang. She emphasized that longevity risk transmission is highly lagged and easily overlooked.
Under the C-ROSS Phase II framework, although the industry can now quantify longevity risk, the results are surprising. Data shows that market risk accounts for the largest share of quantified risks, while insurance risk as a whole represents approximately 30%; due to factors such as hedging, the capital requirement for longevity risk is expected to be less than 5%.
"The extremely low capital ratio not only indicates that longevity risk is currently underestimated but also confirms the vast management growth potential under the expansion of the pension market," Guan Jiaoyang added, noting that while rules are being strengthened for prudence, they are simultaneously unlocking policy benefits.
For example, in adverse longevity risk scenarios, the shock to mortality improvement extends from primarily affecting the first 10 years to the first 30 years. This compels insurers to enhance their precise assessment of long-term liabilities and strengthen capital coverage for longevity risks to ensure adequate solvency.
Additionally, regulators have applied a 10% discount to the minimum capital requirement for longevity risk in exclusive commercial pension insurance products, aiming to channel insurance resources toward retirement protection and support the development of the third pillar of the pension system.
Cailianshe: What are the main challenges currently facing longevity risk management?
Guan Jiaoyang: Weak data foundation, high capital burn pressure, lack of hedging tools, and pricing model bias
According to Guan Jiaoyang, insurance companies face five core pain points in longevity risk management.
Weak data foundation. Although life tables and multi-dimensional experience analyses exist for various business types, the proportion of high-age business underwritten remains low, resulting in insufficient operational experience and data reserves for this segment.
Shortage of lifetime annuities and limited product variety. Guan Jiaoyang points out that current commercial pension annuity products suffer from severe homogenization, with a notable absence of lifetime annuity options. She states: "Current annuity and pension annuity products are relatively basic and highly similar in features. The market lacks customized offerings for specific demographics—for example, lifetime annuities tailored for single older women, as well as accelerated or increasing annuities."
Limited risk transfer tools. The market relies too heavily on traditional reinsurance channels, which offer limited supply, low flexibility, and high upfront costs, making it difficult to effectively diversify long-term risks and thereby constraining rapid business growth.
Difficult asset-liability matching. Pension products typically have ultra-long durations, while the supply of high-quality long-duration assets in China is severely limited. This mismatch can exacerbate insurers' solvency risks and pressure their operational stability.
Insufficient industry management capabilities. Significant gaps exist among industry stakeholders in data governance, actuarial modeling, risk management, and talent development, with a disconnect between awareness and action and a lack of practical management tools and methods.
Facing the dual challenges of longevity risk and declining interest rates, Guan Jiaoyang stated that actuaries must break free from traditional scale-driven mindsets. Strategic focus should shift from mere savings substitution to precise management of longevity risks and diversified product and service offerings.
Cailian Press: What suggestions do you have for establishing a longevity risk transfer mechanism?
Guan Jiaoyang: Drawing on proven practices from mature insurance markets in risk securitization and capital hedging, the key to breaking through lies in "three-party collaborative efforts."
How to effectively manage longevity risk? Guan Jiaoyang benchmarks mature markets such as the US, Europe, and Japan, analyzing advanced practices from Rothesay Life (UK), Achmea Group (Netherlands), Swiss Re, and ATP Pension Fund (Denmark) in risk securitization, derivatives hedging, and annuity management.
Guan Jiaoyang pointed out that the capital market hedging by monopoly institutions, the bundled transfer of "reinsurance + capital markets," and the internal dynamic reserves of the national pension system provide highly valuable references for building a multi-layered, multi-tool longevity risk management framework.
Drawing on China's national conditions, she further proposed that addressing longevity risk requires "collaborative efforts from three parties."
At the insurer level, organizations must strengthen internal capabilities and enhance refined management. Insurers should focus on product innovation and precise pricing, optimize underwriting and risk control systems, deepen digital transformation to boost operational efficiency through big data, and reinforce solvency management to build a robust risk defense framework—ensuring stable operations and sustainable value growth.
Second, at the regulatory level, rules must be refined and market tools diversified. Regulators should accelerate policy innovation, strengthen market-based pricing mechanisms, expand risk hedging instruments and reinsurance channels (e.g., promoting longevity risk securitization), and guide orderly industry competition. Additionally, compliance oversight and consumer protection must be reinforced to foster a fair and transparent market environment.
Third, at the industry research level, collaboration must be deepened to promote co-creation and shared resources. The industry should work together to build data-sharing platforms that break down information silos; strengthen industry-academia-research linkages to establish a talent development system for cross-disciplinary skills; and foster sector-wide exchanges and cross-boundary cooperation to drive overall industry transformation and upgrading.
From learning from international best practices to driving breakthroughs rooted in the local context, Guan Jiaoyang emphasized that effectively managing longevity risks is critical not only for insurers' financial stability but also for the sustainable development of China's third-pillar pension system. Only through collaboration among insurance companies, regulators, and industry research can a comprehensive pension ecosystem be built, contributing the power of insurance to long-term economic and social stability.


