
When performance pressure meets aggressive upfront commission incentives, the KPIs for insurance sales teams can morph into formulas for illegal arbitrage. The recent case in Liangxi District, Wuxi, Jiangsu, involving 5 individuals who fabricated insurance policies to fraudulently extract commissions, exposes the governance risks lurking behind aggressive team incentive models in the insurance industry and offers a stark warning for insurers on commission structure design and agent management.
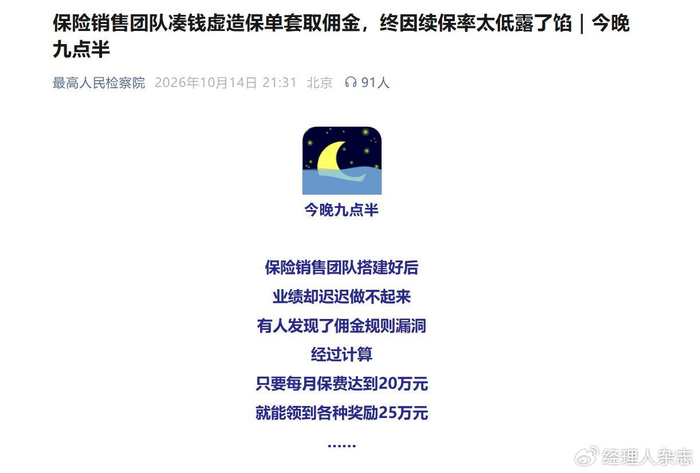
Key case data are clear and verifiable: From 2021 to 2022, Liu and a team of 5 others recruited friends and family as nominal policyholders under the guise of offering free one-year insurance. They jointly paid premiums to fabricate policies, creating 231 fake policies in total. This inflated reported premium revenue by over 220 million yuan and allowed them to extract over 35 million yuan in commissions, new-hire bonuses, startup subsidies, and other rewards. According to the team's projections, achieving a monthly premium target of 20 million yuan—combined with various incentives—yielded net proceeds of 25 million yuan, resulting in total rewards exceeding the principal premium and creating an inherent arbitrage opportunity.
This arbitrage model is simple yet highly deceptive: to rapidly expand new teams, insurers front-load commissions that should be paid over multiple years upon renewal into a single upfront payment in the first year. Combined with starter allowances and tiered management bonuses, this creates a loophole where first-year rewards exceed premiums.
5 individuals listed fake policies under newly recruited agents to claim recruitment bonuses. The scheme operated as a closed financial loop: the gang fronted premiums, which were transferred to policyholders' accounts; the system automatically deducted fees to issue policies. After commissions were paid out, funds were recovered in bulk, the advanced amounts were deducted, and the remainder was split among the conspirators. These fake policies had virtually no genuine coverage needs. One year after issuance, they were mass-cancelled or suspended. The involved teams' renewal rates fell below 30%, far lower than the industry benchmark of 90% for this product. Such anomalies triggered the insurer's risk control review, exposing the fraud.
Legal disputes over the classification of cases during trial proceedings further highlight the complexity of insurance agent employment models. The individuals involved signed agency contracts with the insurance company, which formally establish a civil principal-agent relationship.
However, the investigating authorities pierced through the contractual facade and discovered that 5 individuals were subject to the company's daily performance evaluations and business management while conducting operations under the insurance company's name. This constitutes a de facto employment relationship, satisfying the subject requirements for the crime of occupational embezzlement.
The court ultimately accepted the prosecution's opinion. Person 5 was sentenced to one year and two months in prison, with a one-year-three-month probation period, and fined 10 ten-thousand yuan each. Persons 5 voluntarily returned all illicit gains exceeding 35 ten-thousand yuan and pleaded guilty. This ruling challenges the common misconception that signing an agency contract excludes individuals from being considered company personnel, offering valuable reference for adjudicating criminal cases involving insurance agents.
Although the case has been resolved, the industry's shortcomings it exposed cannot be ignored. Insurers are rushing to expand their business and capture market share, treating short-term volume as the core objective. They have designed aggressive upfront commission schemes that front-load incentive resources while neglecting long-term renewal quality and verification of business authenticity.
Overemphasis on recruitment and premium volume, while neglecting management and policy quality. The lack of dynamic alerts for abnormal team performance, renewal rate fluctuations, and anomalous policyholder follow-ups creates loopholes for organized groups to engage in "short-term selling of long-term policies" and fraudulent insurance purchases. This arbitrage is not an isolated incident; similar insurance black markets have emerged in multiple regions. The core mechanism involves exploiting high first-year commissions and tiered incentives to fabricate performance figures and misappropriate corporate funds.
Case handling goes beyond punishing crimes; it prioritizes industry-wide root-cause governance.
The procuratorial organ issued a prosecutorial suggestion to the insurance company involved, urging it to restructure its commission incentive mechanism. This includes shifting away from an overly front-loaded reward distribution model and aligning commissions and bonuses with long-term policy renewals and genuine customer needs. Additionally, long-term business quality should be integrated into the team performance evaluation system.
Strengthen internal controls for agent onboarding, fund verification, policy follow-ups, and data risk management. Leverage big data analytics to monitor abnormal indicators such as renewal rates, concentrated surrenders, and bulk policies, enabling proactive risk alerts.
The foundation of the insurance industry is genuine risk protection, not just premium figures on paper.
Scale expansion must not come at the cost of systemic loopholes; incentive design must adhere to sound business logic. This case serves as a warning to all insurers: sales incentives are not merely tools for growing scale, and workforce management cannot rely solely on agency contracts to evade core responsibilities.
Only by balancing short-term business growth with long-term risk management, and making policy authenticity and customer retention the core metrics for evaluation, can we prevent policy arbitration cases at the source and safeguard the foundation of stable operations in the insurance industry.


