
Recently, the Shanghai Securities Regulatory Bureau issued Administrative Penalty Decision No. 2026 38, penalizing Yun, a research analyst at an insurance asset management company, for trading based on non-public information (commonly known as "rat trading"). The penalty includes ordering the disposal of illegally held securities and imposing a fine of 50 yuan.
This case spanned 3 years and 8 months. The convergent trading resulted in a loss, and with no illegal gains, the fine of 50 ten thousand yuan represents the statutory minimum.
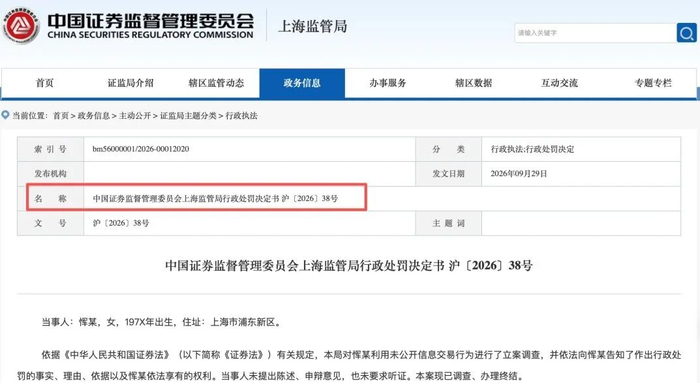
The penalty notice states that Yun [female], born in 197X, worked at a certain asset management company's research department as the portfolio researcher responsible for investment decisions and other duties regarding the portfolio in question. She had access to non-public information related to the portfolio, including holdings and transaction details. The asset management company holds an insurance license.
Between 2022 and 1, Yun controlled two Everbright Securities accounts under the names "Huang Mouju" and "Zhu Mouxiang," using non-public information obtained through their position to conduct securities transactions that converged with the portfolio in question, either independently or by instructing others (explicitly or implicitly). These convergent trades resulted in losses. The primary source and destination of funds for these accounts were Yun and their spouse.
Ultimately, the Shanghai CSRC determined that Yun's actions violated Article 54, Paragraph 1 of the Securities Law and constituted an illegal act as described in Article 191, Paragraph 2 of the Securities Law. Pursuant to Article 191, Paragraph 2 of the Securities Law, individuals who trade using undisclosed information with no illegal gains or with illegal gains under 500,000 RMB shall be fined between 500,000 and 5,000,000 RMB. Since there were no illegal gains in this case, the penalty was set at the lower end of the range.
Insurance asset management companies are other financial institutions as referred to in this Article. Employees of such companies who use their positions to obtain non-public information for trading shall be subject to this Article.
The irony of this fine lies not only in the fact that one can lose money and still be penalized, but also in the identity of the individual involved. Although Yun was nominally a researcher, they were deemed to have been "responsible for investment decisions" regarding the portfolio in question. Typically, investment decision-making authority rests with fund managers, while researchers provide research support—a standard division of labor in most asset management firms. However, it is also true that in some smaller and medium-sized asset management institutions, researchers do play an active role in investment decision-making.
"This enforcement case confirms that the criterion for identifying individuals with access to non-public information in capital markets is substantive decision-making authority, not official job titles," said Bi Mengran, a researcher at Geshang Fund. In this case, Yun's publicly stated title as a research analyst was not used as the basis for determination. Regulators focused on the individual's actual operational authority, finding that Yun participated in investment decisions for the portfolio involved, had access to non-public information such as holdings and trading plans, and was therefore classified as an insider.
Bi Mengran stated that China's asset management industry traditionally builds its information barrier systems based on job levels and departmental divisions. This conventional approach leaves clear regulatory blind spots. Although some research analysts and back-office support staff lack formal titles such as fund manager or investment manager, they are deeply involved in investment research decisions and have access to core trading data. Traditional information barriers only segment permissions by job labels, failing to cover personnel who substantively handle sensitive information, thereby creating compliance vulnerabilities.
Nan Kai University finance professor Tian Lihui also stated in an interview that current information barriers often rely on static role and departmental divisions, overlooking actual power overreach and cross-functional interactions during business workflows. Asset management firms must shift from defining confidentiality based on job positions to defining it based on authority, dynamically tracking information access trails and trade order flows, and precisely delineating the boundaries of persons with access to non-public information.
From a legal perspective, Dong Yaohui, rotating president of the Shenzhen Financial Stability and Development Research Institute, told Shanghai Securities News that this case reflects an enforcement approach to trading on undisclosed information where profit is not a constitutive element: any convergent trading using non-public information obtained through one's position constitutes a violation, regardless of whether it results in gains or losses. Even if there were losses and no illegal income, the statutory minimum fine of 50 yuan remains a mandatory penalty for the violation.
Typically, "rat trading" occurs in licensed financial institutions that hold or have access to large investment portfolios, such as public and private funds. According to incomplete statistics, between 2021 and 2025, the China Securities Regulatory Commission (CSRC) launched investigations into 42 rat trading cases and referred 17 of them to public security authorities. In terms of penalty distribution, the public fund sector remains the most prevalent, though regulatory enforcement is gradually extending to insurance asset management firms and securities companies.
Why are "rat trading" penalties rare in the insurance asset management sector? Tian Lihui explains that the scarcity of such penalties does not indicate lower moral hazard, but rather stems from monitoring barriers such as long investment horizons, low trading frequency, and complex account nesting.
However, monitoring barriers are gradually being dismantled by regulatory technology. Dong Yaohui believes that this case, which involved nearly 4 years of tracking and precise identification of illegal facts, demonstrates the enhanced capabilities of regulators in identifying low-frequency convergence and constructing long-term behavioral profiles. Regulatory technology can now detect anomalous trajectories within massive volumes of low-frequency transactions.
For asset management firms, Dong Yaohui recommends: close the gap in underlying account transparency reporting and identify hidden accounts held by employees and their related parties; break down internal data silos to establish a dynamic sensitive information blocking mechanism covering research, investment, and trading; and develop customized anomaly detection algorithms tailored to the low-frequency trading and long-term holding characteristics of asset management products, building a digital compliance defense aligned with your business logic.
"Defining sensitive information roles should not rely solely on job titles, but rather on the actual access to and influence over non-public information. Whether in research analysis, trade execution, risk control, or performance evaluation, any role that substantively accesses or infers core holdings and trading intent must be classified as a sensitive position," said Dong Yaohui.
Source: Shanghai Securities News
Edited by Dong Wenbo | Managing Editor: Luo Kun


