
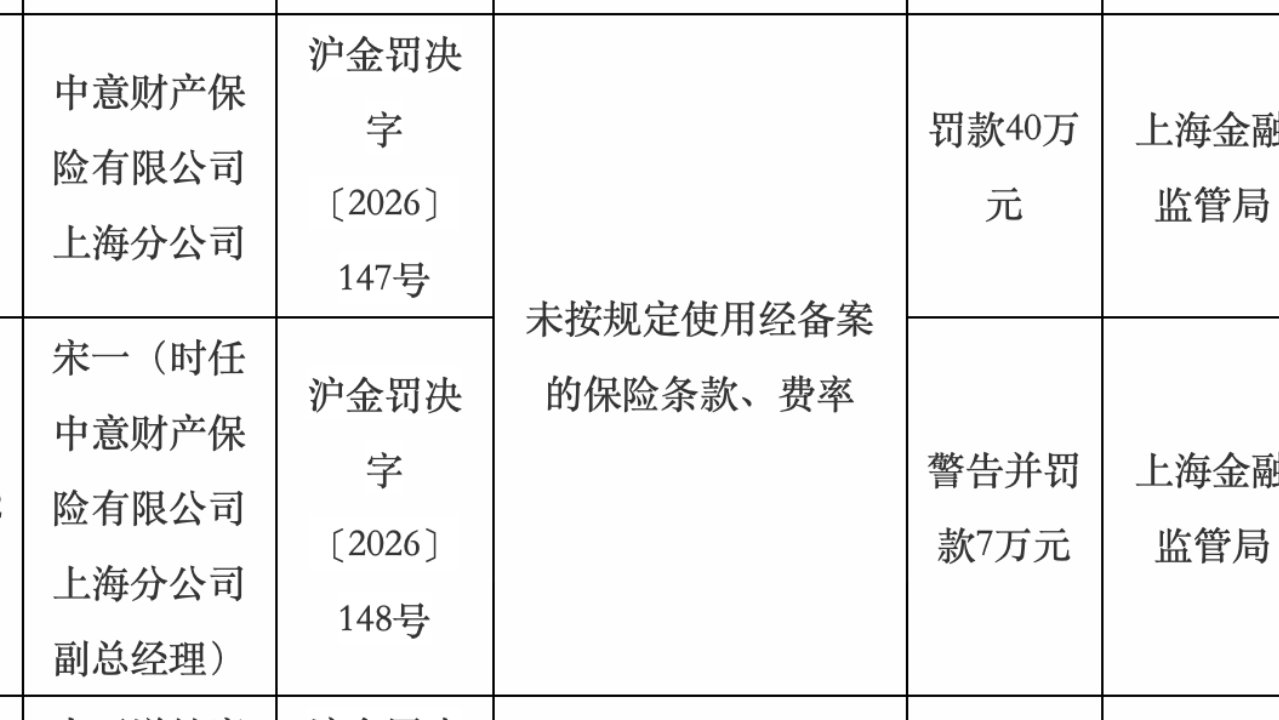
On 2026-10-8, the Shanghai Bureau of the National Financial Regulatory Administration disclosed administrative penalty information. Zhongyi Property Insurance Co., Ltd. (hereinafter "Zhongyi Property Insurance") Shanghai Branch was fined 40 ten thousand yuan for failing to use filed insurance clauses and premium rates as required. Song Yi, then Deputy General Manager of the Shanghai Branch, received a warning and was fined 7 ten thousand yuan. The total fine imposed on the institution and individuals amounted to 47 ten thousand yuan.
This is not the first time a branch of Zhongyi Property & Casualty Insurance has been penalized this year. Previously, its Sichuan branch was fined 40 million yuan for fabricating financial documents, and relevant personnel were also sanctioned. The penalties from both regions address compliance issues in different operational areas: execution of policy terms and rates, and authenticity of financial records.
The Shanghai branch was fined 40 million yuan, and the then-deputy general manager was also penalized.
The two penalty decision numbers are Hu Jin Fa Jue Zi [ 2026 ] No. 147 and No. 148. Both Shanghai Branch and Song Yi violated regulations by using insurance clauses and premium rates that were not filed as required.
Insurance terms define the scope of coverage and exclusions, while rates are directly tied to pricing. From a process perspective, after product filing is complete, actual underwriting must still adhere to the approved terms and rates; filing and usage represent interconnected management stages. The "Measures for the Administration of Insurance Terms and Rates of Property Insurance Companies" also require insurers to strengthen management of terms and rates in use, designating specific departments to monitor, evaluate, and refine them.
Disclosures from the same batch indicate that non-compliance with clause and rate regulations is a common issue among other insurance institutions. Pacific Health Insurance Shanghai Branch was warned and fined 23 million yuan for failing to use filed insurance clauses and rates as required, as well as conducting cross-regional insurance business operations. Dinghe Property & Casualty Insurance Shanghai Branch was also warned and fined 54 million yuan for submitting false financial reports, not using filed clauses and rates properly, and engaging in cross-regional operations. Since fines imposed on both entities cover multiple violations, they cannot be treated as penalties solely for clause and rate non-compliance.
The Sichuan branch was previously fined, with a combined total of 91 million yuan in penalties across both locations.
Another set of penalty data released in 3 this month shows that Zhongyi Property & Casualty Insurance's Sichuan Branch was fined 40 million yuan by the Sichuan Financial Regulatory Bureau for preparing false financial documents. Chen Kuangfei, then acting head and general manager of the Sichuan Branch, received a warning and a fine of 4 million yuan for the same violation. The combined penalties against the institution and individuals totaled 44 million yuan.
Based on the confirmed penalties in Shanghai and Sichuan, the two branches were fined a total of 80 million yuan, the two responsible individuals were fined a total of 11 million yuan, resulting in combined fines of 91 million yuan.
However, the two cases differ significantly. The Shanghai penalty concerns implementation of product terms and rates, while the Sichuan penalty involves authenticity of financial records. Both penalties relate to daily management operations at branch offices, and current managers were held accountable in both instances.
Corresponding rectification measures must be implemented across different stages: issues with terms and rates concern the consistency between product rules and actual underwriting, while financial data issues involve the accuracy and authenticity of business records, expense calculations, and submitted reports.
Registered capital of 16.92 billion yuan, net profit for the first half of the year was less than 300 ten thousand yuan.
The Zhongyi Property Insurance website states that the company was established in Beijing in 2007 with a registered capital of 16.92 billion yuan, wholly owned by Assicurazioni Generali S.p.A. Corporate governance disclosures indicate that the company became a wholly foreign-owned enterprise in 9 2024, and no longer maintains a shareholders' meeting. The company's timeline also shows that its registered capital increased from 13 billion to 16.92 billion yuan in 2025.
From a business scope perspective, Zhongyi Property & Casualty Insurance Company offers property damage insurance, liability insurance, credit insurance, guarantee insurance, short-term health insurance, accidental injury insurance, and related reinsurance services. Products displayed on the official website include motor vehicle insurance, outbound travel insurance, engineering and energy insurance, liability insurance, and cargo insurance, serving both individual and corporate clients.
Engineering and energy insurance covers offshore oil, onshore oil and gas drilling operations, construction machinery loss and installation, and construction projects. Liability insurance includes public liability, product liability, and employer liability. Each product corresponds to specific risks and coverage arrangements; policy selection, rate application, and underwriting review are key components of actual underwriting management.
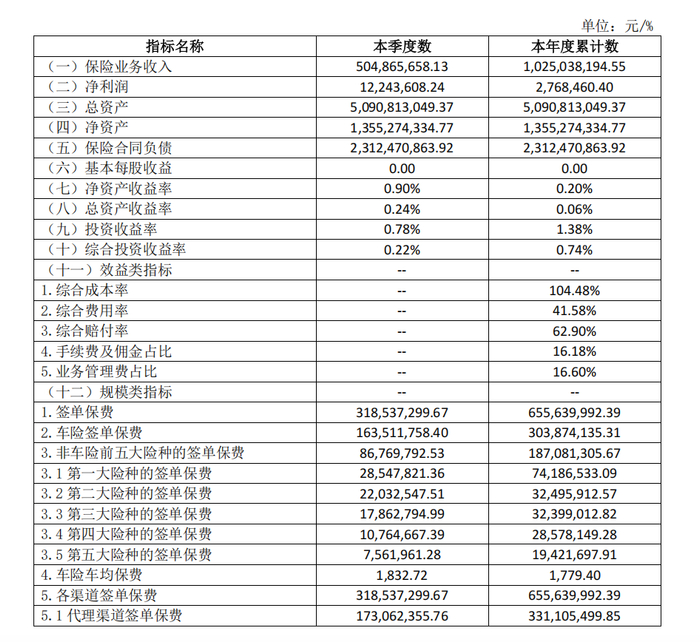
The China-Italy Property & Casualty Insurance Company's solvency report shows that in the first half of 2026, the company generated insurance revenue of 10.25 billion yuan, a year-over-year decline of approximately 0.47%; net profit was 276.85 million yuan, down 74.42% year-over-year. While insurance revenue remained relatively stable, the drop in net profit was significant.
For Zhongyi Property & Casualty, the most immediate issues from this penalty lie in operational execution: whether filed policy terms and rates are used consistently during underwriting, and whether financial records at branch offices accurately reflect actual business activities. The effectiveness of corrective actions following penalties in both regions remains to be disclosed.
(CNA, Jian Yinzhi)


