
Special: Golden Pixiu · 2026 7th Bank-Insurance Cooperation and Development Forum
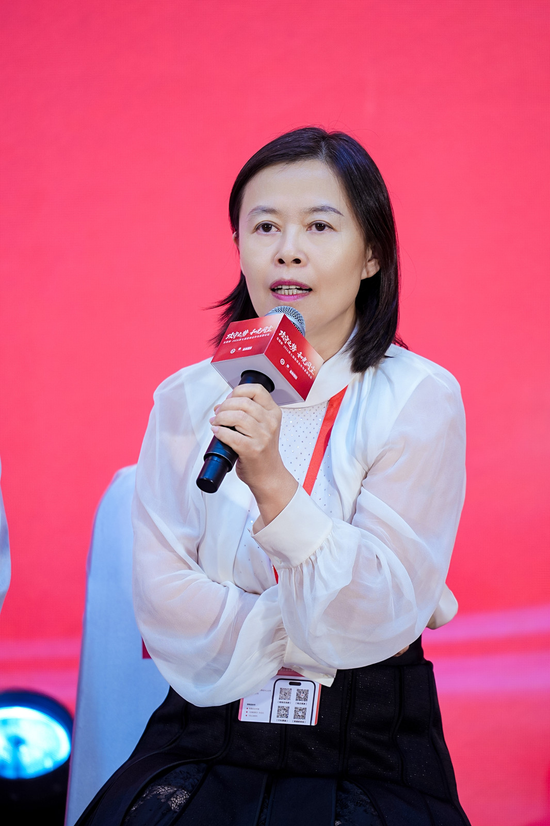
Feng Yunxia believes that after the implementation of "Document 65", the decision between single-premium and regular-premium sales in the bancassurance channel must consider not only market conditions and company strategy but also the reality of the company and its workforce. Long-term customer engagement depends on product selection and the professional capabilities of the team. Under the new regulatory framework, achieving symbiosis among insurance companies, partner banks, frontline teams, and customers has become a core issue of industry-wide concern.
On 2026年9月22日, the 7th Bank-Insurance Cooperation and Development Forum of "Golden Pixiu" · 2026, along with the award ceremony for bank-insurance series awards, was held in Beijing. Hosted by Yiqu Finance Media and "Insurance Enterprise High Reference", this year's forum centered on the theme "Offensive and Defensive Strategies: Harmonizing Light and Dust". Senior leaders from regulatory bodies, banking, and insurance sectors engaged in insightful discussions on the development of bank-insurance cooperation following "Document No. 65".
During the afternoon roundtable, Feng Yunxia, General Manager of the Bancassurance Department at Zhonghui Life Insurance, discussed the positioning of single-premium and regular-premium products, product selection, and frontline professional development following "Document No. 65". She emphasized that under the "reporting and operations alignment" and asset-liability linkage regulatory framework, the value of single-premium products extends beyond scale; it also strengthens bank customer retention, expands the new customer base, and boosts confidence among frontline staff. For long-tail customers, insurers can offer a wider range of choices and more robust professional support. She stressed that in the new regulatory environment for bancassurance channels, the core objective is to build a new ecosystem where life insurers, partner banks, financial advisors, and clients coexist and thrive together.
Dynamic Balance Between Lump-Sum and Periodic Payments
Stickiness and Customer Acquisition Value of Lump-Sum Payments
In 3, the National Financial Regulatory Administration issued "Document No. 65", expanding fee management in the bancassurance channel from commissions alone to include four categories: compensation and incentives for bancassurance specialists, training and customer service fees, and allocated fixed costs. These four categories are now reported and managed separately. Following the implementation of the new regulations on 7 1, the bancassurance market entered an adjustment phase. Industry exchange data shows that in 7, monthly new premium volumes declined year-over-year by approximately 60%, with the decline widening further in 8.
She noted that the balance between single-premium and regular-premium policies is dynamic, requiring consideration of the company's current operational capacity, employee capabilities, and the needs of both banks and customers. Some banks face low deposit pressure and prefer more single-premium products, while others prioritize fee income and favor regular-premium policies. Additionally, bank wealth managers are segmented; younger managers who recently transitioned into the role may handle different products for different clients.
After the implementation of Document No. 65, frontline teams face mounting pressures that can no longer be ignored. Branch activity rates and staff engagement continue to decline, with bancassurance specialists seeing a sharp drop in commission income. Some long-time industry veterans are already leaving. Feng Yunxia worries that once these experienced professionals depart, recruiting new talent will become even more difficult.
However, she doesn't believe the value of single-premium products should be discounted. Single-premium policies strengthen bank stickiness, aid customer acquisition, and give wealth managers and bancassurance specialists a natural entry point to engage clients. Selling insurance is challenging; long periods without sales can be discouraging. A single-premium product helps new agents close their first deal, gradually restoring confidence on the front lines.
The banking sector serves a vast customer base, yet insurance penetration remains low relative to the total asset volume. With regulators prohibiting on-site sales, struggling to sell even simple products erodes frontline confidence in both the industry and their own sales capabilities. Single-premium (lump-sum) products, with their straightforward logic and ease of explanation, serve as an effective tool for helping newly appointed bank wealth managers, entry-level relationship managers, and dedicated insurance agents get up to speed and stay. A科学的期趸 combination strategy leverages regular premiums to build long-term value while using single-premium products to activate branches and nurture new talent. This approach balances the interests of insurers, partner banks, and customers alike, driving the sustainable development of the bancassurance ecosystem through a shared-growth philosophy.
From an operational perspective, Feng Yunxia noted that backed by its shareholder China Investment Corporation, Zhonghui Life Insurance achieved premium volume of over 250 billion yuan in the insurance banking channel last year, with term premiums exceeding 100 billion yuan. In the first quarter this year, business declined significantly, but turned to positive year-over-year growth in the second quarter; the year-over-year decline in term premiums narrowed from 61% to over 30%.
On product supply, she noted that the company typically collaborates with banks by having regional branches submit requirements, after which headquarters conducts research on target banks to jointly develop products. The award-winning "Huiliying" product was developed through this approach and has performed well in the market. This model, where bank-driven demand shapes product design, vividly demonstrates the deep synergy and mutual growth between insurers and banks.
Long-tail customer management
Test product selection and professional expertise
The pricing dynamics on the savings side are shifting. The posted interest rate for fixed-term deposits at state-owned major banks has fallen to around 1.25% for a 3-year term, driving up demand for asset reallocation among households. Starting from 1 in 7, new industry self-regulation standards for insurance product suitability took effect, advancing parallel efforts in product and salesperson qualification grading. Professional expertise is now becoming a prerequisite for frontline business development.
Feng Yunxia explained that Zhonghui Life Insurance currently offers over 20 products, including fixed-income and participating policies with varying terms. Across different banks and stages, these products provide suitable options for financial managers of varying capabilities; a rich selection is essential to serve more long-tail customers.
Amidst intensified homogenization driven by "Document No. 65" and adjustments to assumed interest rates, Zhonghui Life advocates a "one bank, one strategy" approach for differentiated product offerings, precisely aligning resources with each channel's actual operational rhythm. She emphasized that differentiation is not about isolated operations but rather deep collaboration and mutual empowerment between insurers and banks, fostering symbiotic success while respecting the unique characteristics of each channel.
As an insurer, Feng Yunxian believes that insurance companies must provide more tools, including technology adoption, product design, and frontline training. Following the implementation of Document No. 65, strengthening training for insurance company personnel has become especially urgent. She notes that she frequently engages with frontline staff and directly observes their status; some lack understanding of the products themselves. This year, the company has intensified training efforts, delivering programs directly from headquarters to the frontline. The tools and product pricing offered by the company must align with customer needs, bank requirements, and staff capabilities, all focused on elevating professional expertise. Without strong professional competence, even the best tools go unused, leading to significant staff attrition and hindering business growth.
The success of bancassurance ultimately depends on frontline staff. Ensuring income for the external workforce and stabilizing service foundations are key to long-term competitiveness in branch deepening and customer management. Only by aligning efforts among insurers, partner banks, and frontline teams can we achieve true multi-party symbiosis, ensuring every client receives tailored protection and planning.
Feng Yunxia noted that regulation imposes constraints; institutions must deepen their understanding of policies within current conditions and turn challenges into opportunities. Compared to the vast size of bank customer bases, insurance density among Chinese residents remains low, leaving significant room for growth. Only by providing frontline staff with effective tools, quality products, and sufficient professional support can they accurately identify which customers need what coverage.
After the Pangs
The future of bancassurance remains promising.
Industry data shows that new single-premium volumes in bancassurance declined year-over-year by 18.6% over the first 8 months, as the market adjusts to new fee rules. Most institutions share this view: short-term pressure is unavoidable. Lower fees will help reduce customer acquisition costs and improve channel value rates, with growth momentum expected to resume in 2027.
In the forum's concluding outlook session, Feng Yunxia, General Manager of Zhonghui Life's Bancassurance Department, shared her assessment of the bancassurance market for the period after 9 and 10 this year, as well as in 2027. She noted that while stricter "reporting and execution alignment" measures often bring short-term pain, there remains strong demand from banks and insurers, financial advisors and frontline teams, and customers alike. Only by working together can all parties navigate cyclical challenges and share the benefits of high-quality industry development.
Looking to the future, Zhonghui Life will continue to uphold long-termism, refine insurance products tailored for banking channels, and deliver differentiated channel offerings. We will prioritize team development, collaborate with partners to strengthen frontline service capabilities, and work hand-in-hand with our banking partners to build a mutually symbiotic bancassurance ecosystem, jointly ushering in a new phase of high-quality industry growth.
Feng Yunxia concluded that the future of bancassurance remains "bright" with excellent prospects. While pain points are short-term, demand and needs are long-lasting.
Source: Insurance Experts


