
SSE OPTION REPORT
We backtested seven combined spot-futures strategies (covered call, protective put, collar, 95/05 allocation, short put, long butterfly spread, and long calendar spread) along with Huatai-Pinebridge CSI 300ETF ETF. The backtest covers the period from 202/6/10 to 202/6/10. Last week, the CSI 300ETF Huatai-Pinebridge ETF declined. Strategies 95/05 experienced smaller losses. Take-profit was executed on the protective put and collar strategies on 9/28. Results are detailed below:
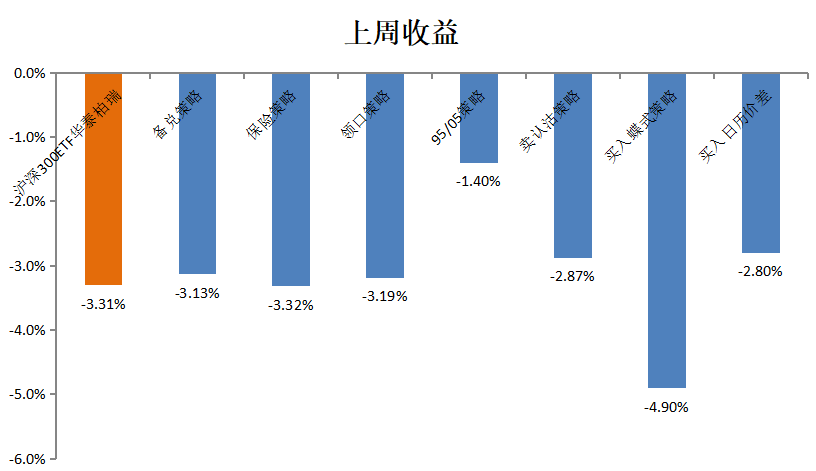
Note: The Protective Put, Collar, Long Butterfly, and Long Calendar Spread strategies include a profit-taking mechanism. See the strategy notes at the end of this document for details.
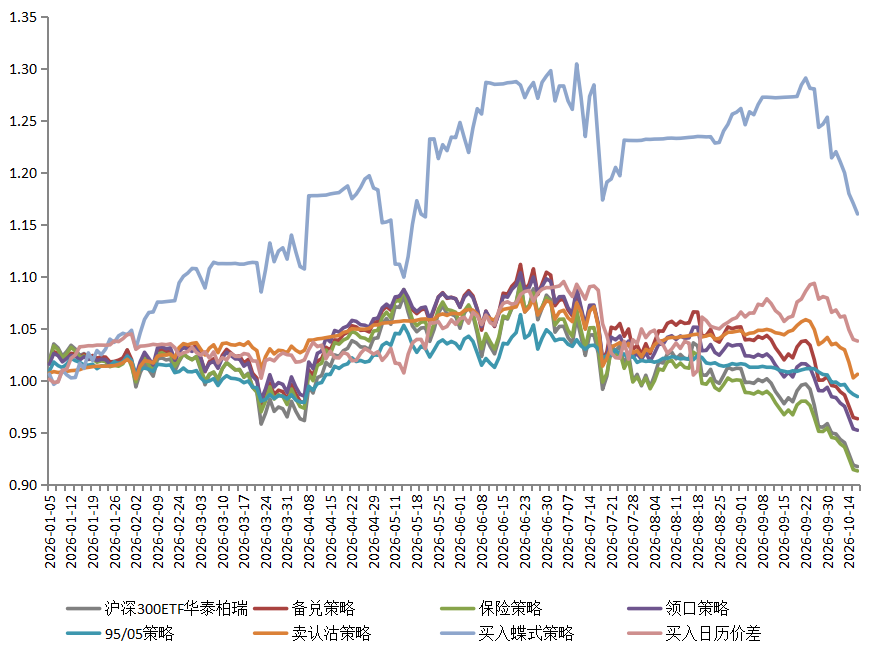
Year-to-date, spot prices have experienced slight volatility with a minor decline. The long butterfly strategy has delivered strong returns. Below are the detailed performance metrics for all seven strategies:
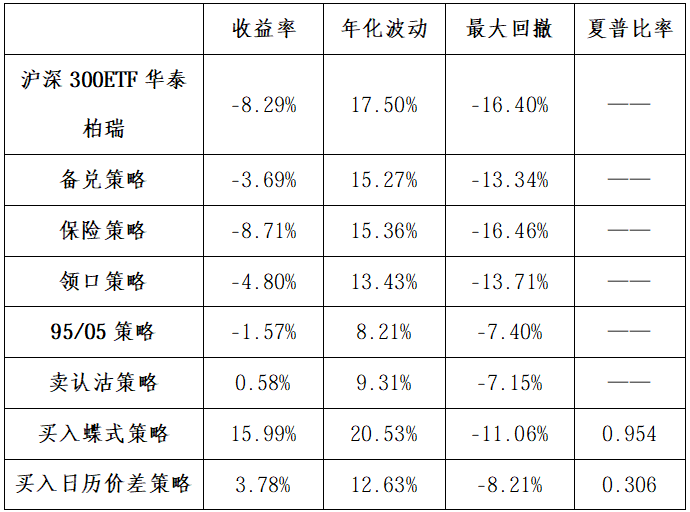
Note: On 2/2, 3/23, 7/2, and 9/28, the insurance and neckline strategy will take profits.
Buy butterfly strategy and take profit on 2/9, 3/6, 4/8, 5/21, 6/9, 7/24, 9/8.
Take profit on the calendar spread strategy on 1/14 and 5/21.
Year-to-Date Combined Spot-Futures Strategy Performance Chart
Comment:
Covered call, protective put, and collar strategy entry and rebalancing: Portfolio base date is 202 5, 12 month 31. Buy 1 hundred thousand units of CSI 300ETF HuaTai Bai Rui spot at the closing price. For the covered call strategy, sell to open 1 out-of-the-money call contracts for the current month with a strike price 5% above the spot at the closing price. For the protective put strategy, buy to open 1 out-of-the-money put contracts for the current month with a strike price 5% below the spot at the closing price. For the collar strategy, buy to open 1 out-of-the-money put contracts for the current month with a strike price 5% below the spot and sell to open 1 out-of-the-money call contracts for the current month with a strike price 5% above the spot, both at the closing price. Thereafter, rebalance on the last trading day of the week prior to each options contract's expiration by closing existing positions and opening corresponding next-month contracts at the closing price. If the P&L of the put options held under the protective put or collar strategy exceeds 50%, close the positions to take profits.
95/05 Strategy Position Building and Rebalancing: The portfolio base date is 202, Year 5, Month 12, Day 31. Allocate 95% of assets to China Fortune Government Bond ETF (511010) and 5% to purchase call options with the furthest maturity that are 5% in-the-money. Rebalance on the last trading day of each quarter end. Reallocate the proportion of ETFs and options based on the total portfolio size on the rebalancing date. Close existing option positions at the closing price and establish new positions in the furthest-maturity contracts at the closing price.
Put Selling Strategy: Position Entry and Adjustment Method. The portfolio starts with 40 million CNY in cash, equivalent to the notional value of approximately 10 CSI 300ETF Huatai-PineBridge Put options contracts. On the close of 202, 5, month 12, day 31, sell 10 out-of-the-money Put options contracts for the current month at a strike price 2.5% below spot (approximately one strike lower) on CSI 300ETF Huatai-PineBridge. Use the remaining cash after deducting the option margin plus the received premiums to purchase Guotai Treasury ETF (511010). Subsequently, adjust positions on the last trading day of each month, one week before the option contract expiration, by rolling the position forward to the next month's contract.
Butterfly Strategy: Entry and Rebalancing Method. Portfolio base date: 202 5, Year 12, Month 31. Allocate 10% of assets to the butterfly strategy (Buy in-the-money call options at 5% strike, Buy out-of-the-money call options at 5% strike, Sell 2x at-the-money call options for next month). Post margin requirements (the long butterfly can be decomposed into a bull call spread and a bear call spread, allowing for portfolio margining), then invest remaining assets in Guotai Bond ETF (511010). Rebalance on the last trading day of each month, one week prior to option expiration. Adjust the allocation between ETFs and options based on total portfolio size. Close existing positions at the closing price and establish new positions for the following month's contracts at the closing price. Take profits by closing all option positions when returns exceed 3 0%.
Buy Calendar Spread Strategy: Entry and Rebalancing Method. Base date for the portfolio is 2025/12/31. Allocate 10% of assets to a calendar spread (sell at-the-money call option expiring this month + buy at-the-money call option expiring furthest out). After posting margin, invest remaining assets in the Treasury ETF Guotai (511010). Rebalance on the last trading day of each month, one week before option expiration. Adjust the allocation between the ETF and options based on total portfolio size on the rebalancing date. Close existing positions at the closing price and establish new positions for next month's contracts at the closing price. Take profit and close option positions when their return exceeds 3 0%.
Sharpe Ratio = (Annualized Return - Risk-Free Rate) / Annualized Volatility.


